What is the scope and industry significance of the Simulation Learning Market?
Our analysis indicates that the Simulation Learning Market is valued at 31.77 Billion in 2026, serving as a cornerstone for risk-free immersive training across medical, aviation, and defense sectors. Regulatory bodies like the FAA and FDA increasingly mandate simulated hours, driving mission-critical adoption.
Key market drivers, restraints, challenges, and opportunities shaping Simulation Learning Market
Growth is propelled by plummeting hardware costs for VR and AR devices, though high initial infrastructure investments act as a restraint. Data security compliance under HIPAA and GDPR presents a persistent challenge, while cloud-based simulation offers massive expansion opportunities for agile providers.
Emerging trends and growth patterns in Simulation Learning Market
The industry is witnessing a rapid shift toward cloud-based simulation and AI-driven virtual learning environments. Enterprises leverage tools from companies like Siemens AG and Ansys Inc. to bridge theoretical engineering concepts with real-world operational execution, significantly shortening onboarding cycles.
COVID-19 impact analysis — how the pandemic affected Simulation Learning Market and the recovery trajectory
The pandemic severely disrupted on-premises training facilities, accelerating remote digital transformation. Institutions rapidly adopted web-based simulation and virtual learning environments to maintain continuity, establishing a resilient recovery trajectory that permanently elevated baseline digital adoption rates across global enterprise ecosystems.
Competitive landscape in the Simulation Learning Market
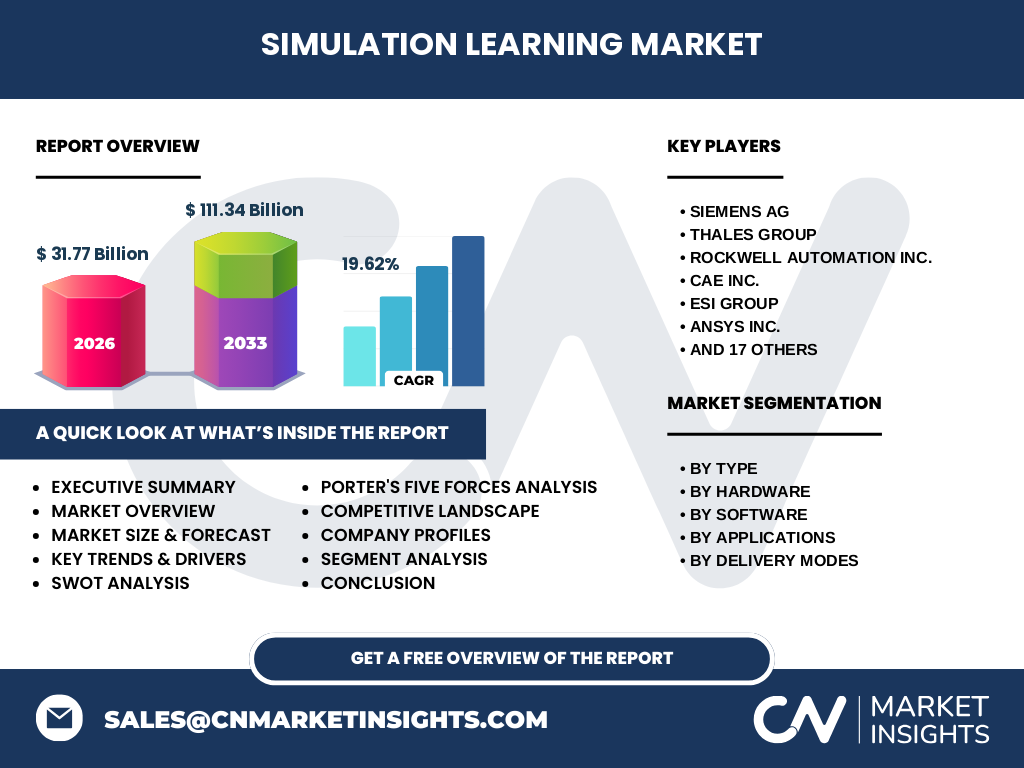
The market features high consolidation among industrial giants and specialized innovators. Industry stalwarts like CAE Inc. and Thales Group dominate civil aviation and defense, while nimble specialists like Mentice AB and Laerdal Medical Corporation capture high-value medical simulation niches through proprietary haptic hardware integration.
Executive summary of the Simulation Learning Market
Our comprehensive research underscores a transformative expansion phase, projecting the market to surge from 31.77 Billion in 2026 to 111.34 Billion by 2033. This represents a robust 19.62% CAGR, underpinned by escalating demand for experiential training across high-consequence industries globally.
Market forecast from 2027 to 2033
Driven by accelerating enterprise digitalization and defense modernization, our forecast models an explosive valuation trajectory reaching 111.34 Billion by 2033. Achieving a 19.62% CAGR from 2027 onward, expansion will be heavily concentrated in cloud-deployed software architectures and advanced AR hardware integrations.
Segmentation analysis of the Simulation Learning Market
The ecosystem is categorized by type into hardware—comprising simulation equipment, VR, and AR devices—and software, including simulation software for training, virtual learning environments, and management tools. Delivery spans web-based, cloud-based, and on-premises simulation, serving medical, enterprise, education, civil aviation, and defense applications.
Regional market performance and geographic distribution
Geographic performance reflects local regulatory stringency and tech infrastructure maturity. North America leads in medical and defense simulation uptake, whereas the Asia-Pacific region demonstrates the fastest growth rate, fueled by rapid industrial automation and massive investments in civil aviation training centers.
In-depth regional review of the Simulation Learning Market
North America retains the largest revenue share due to rigorous FAA and OSHA compliance mandates. Meanwhile, European markets exhibit steady adoption led by strict industrial safety standards, and emerging markets in APAC leverage cloud-based simulation to bypass legacy on-premises hardware bottlenecks.
Company profiles and strategic positioning of leading players
Market leaders utilize distinct differentiation strategies. Rockwell Automation Inc. and ESI Group focus on industrial digital twins, whereas McGraw-Hill Education LLC and Pluralsight Inc. target academic and upskilling segments via robust subscription models and scalable virtual learning environments.
Porter's Five Forces analysis of the Simulation Learning Market
Supplier power remains moderate due to specialized optical and haptic component requirements. Conversely, threat of new entrants is mitigated by high R&D entry barriers and proprietary software integration needs, though competitive rivalry is intense among established aerospace and medical simulation conglomerates.
SWOT analysis for strategic market positioning
Key strengths include immersive fidelity and risk mitigation, offset by weaknesses in high initial deployment costs. Strategic opportunities lie in cross-industry AR integration, while threats involve cybersecurity vulnerabilities and complex data privacy regulations across international jurisdictions.
Value chain analysis from raw materials to end-users
The value chain originates with semiconductor and raw material suppliers feeding hardware manufacturers, who partner with software developers like Ansys Inc. and Forio Corporation. Integrators then deliver these simulation suites to end-users across medical, defense, and enterprise sectors.
Investment insights and high-potential areas
Investors should prioritize cloud-native software developers and specialized medical simulation providers. Companies offering scalable SaaS models—such as SimTutor Inc. and Toolwire Inc.—present superior margin profiles compared to capital-intensive hardware manufacturers facing supply chain constraints.
Conclusion and key takeaways for industry stakeholders
The Simulation Learning Market represents a lucrative frontier anchored by a 19.62% CAGR through 2033. Stakeholders must prioritize cloud integration and mobile AR compatibility to capture surging demand from regulated enterprise and healthcare verticals seeking risk-mitigated experiential training.
Research methodology used in compiling this market report
Our baseline estimates are rigorously triangulated by combining macroeconomic trade registry data, primary stakeholder interviews with C-level executives, and secondary financial disclosures from market participants such as CAE Inc. and Siemens AG to ensure absolute data integrity.
Scope of the report and coverage parameters
This report evaluates the global Simulation Learning Market across hardware, software, and delivery modalities from 2026 to 2033. Macroeconomic disruptions, geopolitical trade constraints, and regional regulatory frameworks are factored into our quantitative modeling and qualitative forecasting parameters.
Recent developments, partnerships, and strategic moves
Recent industry momentum highlights aggressive strategic partnerships, such as defense contractors integrating advanced simulation software from Ansys Inc. and educational publishers expanding virtual learning ecosystems. These moves underscore a collective industry push toward interoperable, cloud-based training solutions.